How Much Does Rehab Cost? Paying for Addiction Treatment in Lexington, KY
For many people, the decision to seek addiction treatment is emotional and financial. Families often worry about insurance coverage, deductibles, time away from work, payment options, and whether treatment will create additional financial stress.
Those concerns are common, but they do not necessarily mean treatment is out of reach. Understanding insurance benefits, levels of care, and available payment options can make the process much clearer.
People who need detox, medication management, or closer medical monitoring may have different treatment costs than people appropriate for outpatient care.
The amount of time a person remains in treatment depends on clinical progress, relapse risk, mental health needs, and recovery goals.
Does Insurance Cover Rehab?
In many cases, health insurance provides some level of coverage for addiction and mental health treatment. Exact benefits depend on the individual policy, network status, medical necessity, deductible, coinsurance, copays, preauthorization requirements, and recommended level of care.
Insurance may help cover services such as outpatient treatment, therapy, medication-assisted treatment, mental health counseling, medical detox, and dual diagnosis care depending on the plan.
Insurance verification can help families understand likely benefits before treatment begins.
Some individuals choose to pay directly for treatment when insurance is unavailable or does not cover the recommended service.
Payment Arrangements
Depending on the provider, payment plans or other financial arrangements may be available to make treatment costs more manageable.
Employer or Family Support
Some people use employer assistance programs, family support, or other personal financial resources to help cover treatment.
Community Resources
State-funded, community-supported, or nonprofit treatment resources may be available for some people depending on eligibility and location.
The Financial Cost of Delaying Treatment
When people think about rehab costs, they often focus only on the immediate price of treatment. Untreated addiction can also create significant long-term financial consequences.
Emergency room visits and hospitalizations
Legal problems and court costs
Lost income or unemployment
Housing instability
Ongoing spending on alcohol or drugs
Mental health crises and medical complications
Relationship and family disruption
For some people, entering treatment earlier may reduce the larger emotional, medical, and financial damage caused by prolonged addiction.
Why Outpatient Treatment May Be More Accessible
Partial Hospitalization Program (PHP)
PHP provides intensive daytime treatment without requiring every client to live onsite, depending on clinical appropriateness.
Many people struggling with substance use are also dealing with anxiety, depression, trauma, PTSD, panic symptoms, grief, or chronic stress. These concerns can influence both the recommended level of care and the services needed during treatment.
Integrated dual diagnosis treatment addresses addiction and mental health together rather than treating them as unrelated issues.
Many insurance plans provide coverage for medically necessary addiction and mental health treatment. Exact benefits depend on the policy, network status, deductible, coinsurance, authorization requirements, and level of care.
What if I cannot afford inpatient or residential rehab?
Outpatient treatment, payment arrangements, healthcare financing, private pay options, employer assistance, community resources, or other alternatives may make treatment more financially accessible.
Is outpatient rehab less expensive than inpatient treatment?
Often, yes. Outpatient treatment generally does not include the cost of 24-hour housing and supervision, although actual costs vary by program and clinical needs.
Can addiction treatment save money long term?
For some people, treatment can reduce costs associated with emergency care, legal problems, job loss, hospitalization, ongoing substance use, and other consequences of untreated addiction.
Can I verify insurance before committing to treatment?
Yes. Insurance verification can help clarify potential benefits, network status, authorization requirements, and estimated financial responsibility before treatment begins.
What does deductible mean for rehab coverage?
A deductible is the amount a member may need to pay for covered healthcare services before the insurance plan begins paying according to the policy terms.
What is coinsurance?
Coinsurance is a percentage of covered healthcare costs that the member may be responsible for after applicable deductible requirements are met.
Does insurance cover medication-assisted treatment?
Some plans cover medication-assisted treatment when medically necessary, but coverage varies by medication, provider, network status, and policy.
Does insurance cover dual diagnosis treatment?
Many plans cover behavioral health and mental health services, but exact coverage depends on the policy and medical necessity.
How do I find out what treatment will cost me?
The most reliable first step is insurance verification followed by a review of the recommended level of care and expected out-of-pocket responsibility.
Explore Addiction Treatment and Insurance Options in Lexington, KY
Financial uncertainty should not prevent you from asking what treatment options may be available. Lexington Addiction Center can verify insurance, explain levels of care, and help you understand possible next steps.
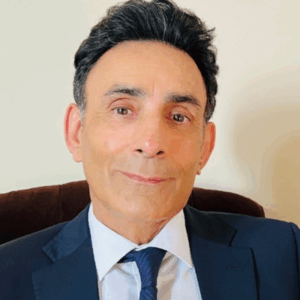
Dr. Vahid Osman is a Board-Certified Psychiatrist and Addictionologist with extensive experience treating mental illness, chemical dependency, and developmental disorders. Dr. Osman trained in Psychiatry in France and in Austin, Texas. Read more.
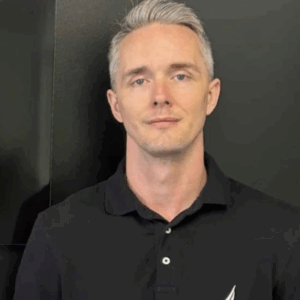
Clinically Reviewed By
Josh Sprung, L.C.S.W.
Board-Certified Clinical Social Worker
Joshua Sprung serves as a Clinical Reviewer at Lexington Addiction Center, bringing a wealth of expertise to ensure exceptional patient care. Read more.
The Joint Commission Awarded The Gold Seal of Approval® for meeting rigorous performance standards in safety, quality, and patient care.
LegitScript Certified Validates compliance with laws and regulations, confirming transparency and accountability in addiction treatment marketing.
BBB Accredited Demonstrates ethical business practices, client satisfaction commitment, and a trusted reputation in the community.
Psychology Today Verified Verified listing on Psychology Today, a trusted directory for addiction treatment providers and behavioral health centers.
HIPAA Compliant Ensures all patient health information is protected and managed under strict federal privacy and security standards.
NAATP Member Lexington Addiction Center is a proud member of the National Association of Addiction Treatment Providers (NAATP).
5-Star Google Reviews Recognized for consistent 5-star ratings, reflecting excellent care and trusted patient experiences at Lexington Addiction Center.
Help.org Recognition Recognized by Help.org for quality addiction treatment services and community impact.
Yes, Your Insurance Covers Detox and Rehab Treatment
Complete a free, confidential Verification of Benefits to learn more about what resources may be available to you.
Contact Us Today
Addiction and co-occurring disorders don’t have to control your life. Lexington Addiction Center is waiting with open arms to give you the tools necessary for lasting change. Reach out to us today to learn more.